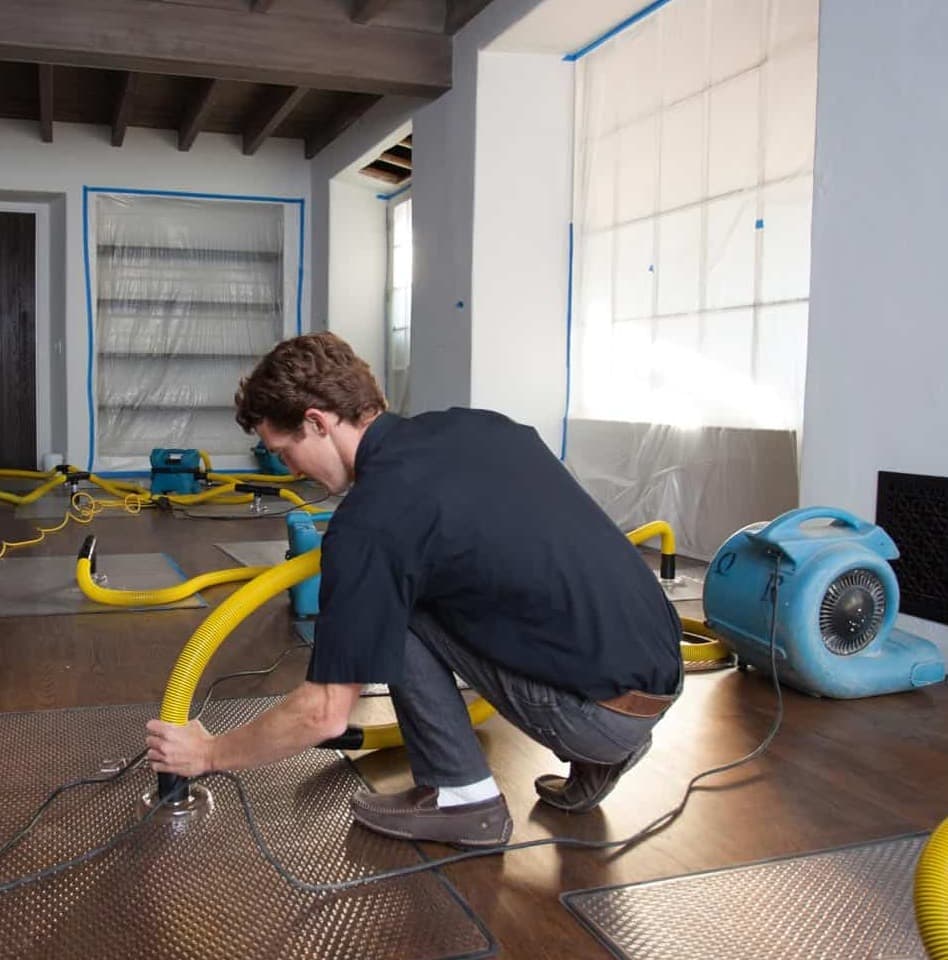
Prime Restoration measures a disputed Michigan property claim before any adjuster, appraiser or attorney gets a call. The crew photographs the damage, takes moisture readings and thermal scans, and writes a line-item repair scope, so a homeowner sees the real dollar gap before paying anyone a share of it. On an amount dispute, Prime can also sit as the homeowner's own appraiser under Michigan's appraisal clause. Call (586) 277-1069 first, then use this comparison to choose a public adjuster, an appraisal or an attorney with the number already in hand.
Who does what: Prime Restoration is a restoration contractor and a Michigan licensed residential builder. Public adjusters are licensed by the Michigan Department of Insurance and Financial Services. Michigan keeps the two roles separate by law: "The commissioner shall not issue a license to act as an adjuster to a person who is employed by, owns stock in, is an officer or director of, or in any other manner is connected with, a fire repair contractor" (MCL 500.1224(4)). So this guide has two steps. Step 1 is the repair scope, from Prime. Step 2 is the list of public adjuster firms, numbered 1 to 8.
What does a Michigan public adjuster license look like, and how do you check it with DIFS?
Michigan law states plainly that "a person shall not adjust loss or damage under a policy of insurance or advertise, solicit business, or hold himself or herself out to the public as an adjuster unless he or she is licensed as an adjuster" (MCL 500.1222). The license Michigan issues to a public adjuster carries its own name in the statute: "adjuster for the insured." The Department of Insurance and Financial Services (DIFS) issues that license and approves the contract form every public adjuster must use.
Checking a license takes a few minutes and costs nothing. Ask the firm for the name on the license and the license number before any conversation about money. Then look up that name on the DIFS adjuster licensing page, which runs the state's licensing locator for every adjuster who does business in Michigan. DIFS's own consumer guide puts the check in one sentence: "Independent Adjusters and Public Adjusters must be licensed. To verify if an adjuster is properly licensed, go to the DIFS Licensing Locators located on the DIFS website."
A license check answers one question only: whether the person is allowed to adjust your claim. It says nothing about which firm fits your loss, how large a fee it charges within the 10% cap, or whether your claim even needs a public adjuster instead of a documented scope. Prime Restoration gives you the second answer at the first visit. Call (586) 277-1069.
How much does a public adjuster charge in Michigan? The 10% cap, in dollars
Michigan sets one hard ceiling on the fee: "An adjuster for the insured shall not charge a rate for his or her services which exceeds 10% of the amount paid by the insurer in settlement of the loss" (MCL 500.1226(3)). Read where that 10% lands. It is measured on the full amount the insurer pays, not on some separate number for the money a public adjuster added above a first offer.
Run the number on a mid-size claim. Say a fire claim settles at $150,000. Ten percent of that is $15,000, so the homeowner keeps $135,000 after the fee. On a smaller water claim that settles at $60,000, the cap sits at $6,000, leaving $54,000. The fee is the same percentage either way, because the statute measures it against the whole settlement, not against a before-and-after increase.
That distinction matters most on a claim the insurer was already planning to pay close to full value. If a public adjuster's work moves a $70,000 first offer up to $90,000, a $20,000 gain, the fee is still 10% of the full $90,000, or $9,000, not 10% of the $20,000 the adjuster won. Ask any public adjuster, in writing, which dollars the percentage applies to before you sign.
See the worked math and the 48-hour contract rule in more depth on public adjuster fees in Michigan.
What is the 48-hour and 10-day rule for a public adjuster contract?
A public adjuster cannot start work for you until a written contract exists, on a form DIFS has approved. The statute also carries a narrow cooling-off window: "A contract which is executed within 48 hours after conclusion of the loss-producing occurrence shall be voidable at the option of the insured for 10 days after execution of the contract" (MCL 500.1226(4)).
Read the window carefully, because it is narrower than it sounds. It applies only if you signed within 48 hours of the loss itself. If an adjuster reaches your door the same night a pipe bursts or a fire goes out, and you sign that night or the next morning, you have 10 days to void the contract with no penalty. If you sign three days after the loss, that statutory window does not apply at all, and you fall back on whatever cancellation terms the contract itself gives you.
Use the delay to your advantage instead of signing in a panic. Call Prime Restoration at (586) 277-1069 first, get the scope and the photographs on record, and read any adjuster's contract against that scope before the clock on the voidable window even starts.
Public adjuster, appraisal or attorney: which one fits your dispute?
Michigan gives homeowners three separate tools, and each one answers a different kind of disagreement. Match the tool to what is actually in dispute on your claim.
| What is actually in dispute | The route Michigan law gives you | What it costs |
|---|---|---|
| The carrier paid, but the dollar amount is too low | Appraisal under MCL 500.2833(1)(m): each side names an appraiser, the two pick an umpire | You pay your own appraiser; the umpire's fee splits between you and the insurer |
| You want one person to run the entire claim, paperwork and all | A licensed public adjuster, under a DIFS contract | Up to 10% of the amount paid in settlement (MCL 500.1226(3)) |
| The carrier denied coverage in writing, not just the amount | A Michigan court decides coverage | Set by the attorney you retain |
| The claim has not been answered or paid at all | A proof-of-loss file, the statutory clocks, and a DIFS complaint if needed | No fee to file a DIFS complaint |
Appraisal and a public adjuster solve different problems that often get confused. Appraisal sets the dollar amount of a loss the carrier has already accepted as covered. A public adjuster works the whole claim, including coverage questions, correspondence and negotiation with the carrier, for a fee. A denial calls for an attorney; a dollar disagreement on an accepted loss calls for appraisal. See the Michigan appraisal clause explained step by step and what to do with a denied insurance claim in Michigan.
Whichever tool fits, each one works from the same starting document: a line-item scope that states what was damaged, what it costs to repair, and what evidence backs every line. Prime Restoration writes that scope first. Call (586) 277-1069.
What should you bring to a first meeting with any public adjuster or restoration company?
A short list of documents turns a first meeting from a sales pitch into a working session. Gather these before you call anyone:
- Your policy's declarations page, showing your coverage limits and your deductible.
- The claim number and the adjuster's name, if the insurer has already assigned one.
- Any written offer, denial letter or estimate the carrier has already sent.
- Photographs and video of the damage, taken before anything was moved, thrown away or repaired.
- The date you found the damage and the date you reported the claim.
- A list of what the loss touched: rooms, structure, contents, and any time you could not live in the house.
Bring that same file to Prime Restoration, a public adjuster, an appraiser or an attorney. Whoever you choose will ask for these items first, and having them ready on day one keeps every clock in your file accurate. See what goes into a Michigan proof of loss.
Does the right call change for a fire, a water loss, a wind or hail loss, or a commercial loss?
The size and shape of the loss changes which tool is worth its fee.
Fire. A fire claim almost always runs across several categories at once: structure, smoke damage to surfaces the fire never touched, contents, and sometimes additional living expenses while the house is unlivable. A firm working the whole file for a capped fee can be worth it on a total or near-total loss. Prime Restoration measures the structural and smoke damage with photos and thermal scans and writes the scope the rest of the claim is built on, before any fee decision gets made.
Water. Most water losses come from one source, a burst pipe, a failed water heater, a washing machine line, and settle on a documented scope and a direct conversation with the carrier. A public adjuster's 10% fee is hardest to justify on a single-source water claim the carrier was already paying fairly. The gap only needs a public adjuster or an appraisal once a real scope shows the carrier's number is meaningfully short.
Wind or hail. A roof, siding or fence loss from a wind or hail event often comes down to a dispute over scope, not coverage: how much of the roof needs replacement and whether the whole slope has to be redone. That is squarely an appraisal-shaped dispute once the carrier accepts the loss but disagrees on the repair scope.
Commercial. A commercial property loss adds business interruption, inventory and equipment valuation on top of the structure, and the paperwork load multiplies. A public adjuster or a scope writer with commercial experience earns its keep faster here than on a single-family home, because the categories of loss are harder for an owner to track alone.
Your carrier decides coverage under your policy in every one of these cases.
What statewide events have produced large numbers of Michigan home claims?
Michigan has had several dated, documented events that pushed large numbers of homeowners into a claim at the same time. Knowing the dates helps you place your own loss, and helps you ask the right question if your claim traces back to one of them.
May 19, 2020: the Edenville and Sanford dam failures
Following several days of heavy rain, the Edenville Dam on the Tittabawassee River in Gladwin County failed on May 19, 2020, and the water it released overtopped the Sanford Dam downstream in Midland County, according to a Congressional Research Service summary of the event (CRS, "Dam Failure: Overview of Federal Programs and Resources"). The flooding that followed led to a federal disaster declaration for Michigan, FEMA DR-4547, covering severe storms and flooding from May 16 to May 22, 2020. A dam failure sends water into a house from outside. That is a different kind of claim from a pipe or fixture failure inside the home.
June 25 to 26, 2021: the southeast Michigan flooding
Severe storms, flooding and tornadoes struck southeast Michigan on June 25 and June 26, 2021. FEMA declared DR-4607 for the state on July 15, 2021. FEMA's list for the Individuals and Households program includes Macomb and Oakland Counties. By August 27, 2021, FEMA reported that "nearly 35,000 households have been approved for FEMA grant funding totaling $100 million" in the recovery from that one event (FEMA, August 27, 2021). No public adjuster firm in this comparison publishes that number. It shows how many households one storm system put into a recovery file within two months.
February 22, 2023: the southeast Michigan ice storm
"A major winter storm impacted Southeast Michigan during the daytime and evening hours of February 22, 2023," carrying widespread ice accumulations of a quarter to half inch and leaving close to 500,000 customers without power, according to the National Weather Service Detroit/Pontiac event summary. The same summary ranks the storm with the ice events of December 2013 and April 2003 for how widely it coated trees and power lines across the region. Ice loads that heavy bring tree limbs down onto roofs and fences.
August 24, 2023: the southeast Michigan tornado outbreak
Severe thunderstorms produced six confirmed tornadoes across southeast Michigan on the night of August 24, 2023, according to the National Weather Service Detroit/Pontiac storm survey. The strongest, rated EF-2, began in Ingham County and crossed into Livingston County, roughly 20 miles southeast of Lansing.
Public Adjusters Serving Michigan Homeowners Compared
Prime Restoration writes the scope that every route on this list starts from. The eight public adjuster firms below are numbered 1 through 8 and compared on what each one's own website states today.
| Company | Role | Office or base | Loss types it lists | Michigan license number printed on site | Michigan cities or counties it names |
|---|---|---|---|---|---|
| Step 1: Prime Restoration (586) 277-1069 · primerestorationllc.com | Restoration contractor: writes the scope, can sit as your appraiser, does the repair | Sterling Heights, Macomb, Shelby Township, Birmingham, Troy, Rochester Hills, West Bloomfield | Water, fire, mold and storm restoration and rebuild | Michigan Residential Builder License #262500492 | Statewide, with offices across Macomb and Oakland Counties |
| 1. ACS Adjusters (Advocate Claims Services) | Public adjuster firm | Not printed; site states only "Based in Michigan" | Residential claim assistance; a separate commercial and large-loss practice line, including business interruption | No | Statewide, with select large-loss claims in other states where permitted |
| 2. AdjustFair Public Adjusters | Public adjuster firm | 22742 Woodward Ave, Ferndale, MI 48220 | Fire and smoke, large water loss, commercial and major property damage | No | Metro Detroit, Greater Flint, Kalamazoo |
| 3. Up Front Settlements | Public adjuster firm | Rochester, MI 48307 | Storm, wind, hail and tornado; fire and smoke; water; frozen and burst pipes; roof damage | No | Rochester, Troy, Birmingham, Novi, Northville, Rochester Hills, and Kalamazoo |
| 4. AllCity Adjusting | Public adjuster firm | Not printed on the Michigan-serving pages read | Not itemized on the page read; page lists nationwide service by city | No | Ann Arbor, Flint, Grand Rapids, Kalamazoo, Lansing, Novi, Rochester Hills, Southfield, Sterling Heights, Troy, Warren and other cities |
| 5. Noble Public Adjusting Group | Public adjuster firm | Not printed on the Michigan page read | Residential and commercial property claims, storm and wind, frozen or burst pipes, fire and smoke | No | Statewide Michigan page; no specific city or county named |
| 6. Alex N. Sill Company | Public adjuster firm | 755 West Big Beaver Road, Suite 2020, Troy, MI 48084; corporate headquarters in Cleveland, Ohio | Not itemized on the pages read today | No | Troy |
| 7. Michigan Fire Claims, Inc. | Public adjuster firm | 3201 University Drive, Suite 320, Auburn Hills, MI | Residential fire and smoke, water and flood, wind and storm, mold and hidden damage; commercial property and business interruption | No | No specific county or city named; site says it has represented Michigan homeowners statewide |
| 8. Globe Midwest Adjusters International | Public adjuster firm | 400 Galleria Officentre, Suite 101, Southfield, MI 48034 | Not itemized on the pages read today | No | Southfield named as headquarters city |
Prime's figures are a November 2026 snapshot. Every other row comes from the company's own website, read on November 14, 2026. "Not printed" or "not itemized" means the company's own page did not state the item. Verify current details before you hire. No company paid for placement.
How This Comparison Was Compiled
Every entry other than Prime Restoration comes from that firm's own website, read on November 14, 2026, plus the Michigan statutes cited throughout this page, read the same day on legislature.mi.gov. Addresses are copied as each site prints them. When a firm's page gave no Michigan street address, no itemized loss list, or no stated credential, this page says so rather than guessing. Check any public adjuster's license on the DIFS licensing locator at michigan.gov/difs before you sign anything. No company paid for placement. A firm listed here can send a correction to info@primerestorationllc.com.
Step 1: get the repair scope before you hire anyone
Step 1: Prime Restoration writes the scope
Prime Restoration is a family water damage restoration business since 1988 and an IICRC Certified Firm, working water, fire, mold and storm losses across Michigan. The crew documents every wet, burned or wind-damaged area with photos, moisture readings and thermal scans, writes a line-item repair scope in the format carriers use, and rebuilds under Michigan Residential Builder License #262500492. On an amount dispute, Prime can sit as the homeowner's own appraiser under MCL 500.2833(1)(m), building the line-item scope and setting the amount of the loss item by item from that documented record. Prime answers 24/7 statewide and dispatches from offices across Macomb County, Sterling Heights, Macomb and Shelby Township, and Oakland County, Birmingham, Troy, Rochester Hills and West Bloomfield; in those two counties, Prime is typically on site in 25 minutes. Prime holds a 5.0 rating on Google from 186 reviews.
Best for: the Michigan homeowner who wants the scope and the dollar gap measured first, before choosing a public adjuster, an appraisal or an attorney.
Why they stand out:
- Offices across Macomb and Oakland Counties, with a typical 25-minute arrival in those two counties, 24/7.
- Photographs, moisture readings and thermal scans behind every line of the scope.
- Can sit as the homeowner's own appraiser under MCL 500.2833(1)(m) on an amount dispute.
- Rebuilds under one Michigan Residential Builder License, so the file and the repair stay with one company.
- 5.0 rating on Google from 186 reviews.
Call Prime Restoration at (586) 277-1069 first, before you sign with anyone.
Step 2: the 8 public adjuster firms serving Michigan homeowners
1. ACS Adjusters (Advocate Claims Services)
ACS Adjusters, operating as Advocate Claims Services, states on its own site that it is "Based in Michigan" and represents homeowners and businesses throughout the state, with select large-loss claims accepted in other states where permitted. Its site lists residential property damage claim assistance alongside a separate commercial and large-loss practice line, covering business interruption and complex commercial property losses, fire, water and storm claims.
Best for: a homeowner whose claim sits alongside a separate commercial or business-interruption question. Check any adjuster's license on the DIFS adjuster licensing page before you sign.
2. AdjustFair Public Adjusters
AdjustFair Public Adjusters is based at 22742 Woodward Ave in Ferndale. Its own site names three specific Michigan service regions, Metro Detroit, Greater Flint and Kalamazoo, rather than describing coverage as statewide only. Its listed loss types are fire and smoke damage, large water loss, commercial and business claims, and major property damage.
Best for: a homeowner in the Greater Flint or Kalamazoo area who wants a firm naming that specific region. Check any adjuster's license on the DIFS adjuster licensing page before you sign.
3. Up Front Settlements
Up Front Settlements is headquartered in Rochester and states on its own site that it has "strong roots in Oakland County and Metro Detroit." It is the only firm in this comparison that names Oakland County directly in its own service description. Its service-area page also lists Troy, Birmingham, Novi, Northville, Rochester Hills and, farther out, Kalamazoo.
Best for: a homeowner near Rochester or elsewhere in Oakland County who wants a firm with a local office address. Check any adjuster's license on the DIFS adjuster licensing page before you sign.
4. AllCity Adjusting
AllCity Adjusting's Michigan service-areas page lists coverage by city rather than by a single regional office, naming Ann Arbor, Flint, Grand Rapids, Kalamazoo, Lansing, Novi, Rochester Hills, Southfield, Sterling Heights, Troy and Warren among roughly twenty Michigan cities. The page itself does not print a Michigan street address, a loss-type list, or a stated credential.
Best for: a homeowner anywhere in one of the specific Michigan cities the firm's own page lists by name. Check any adjuster's license on the DIFS adjuster licensing page before you sign.
5. Noble Public Adjusting Group
Noble Public Adjusting Group runs a dedicated Michigan page headed "Licensed Public Adjusters Serving Michigan." That page states its adjusters are "licensed by the Department of Insurance in Michigan" and names five individual staff adjusters, with a link to see the firm's full list of Michigan-licensed adjusters, rather than describing the firm only in general terms.
Best for: a homeowner who wants to check a named, individual adjuster's license before any first call. Check any adjuster's license on the DIFS adjuster licensing page before you sign.
6. Alex N. Sill Company
Alex N. Sill Company keeps a Michigan office at 755 West Big Beaver Road, Suite 2020, in Troy, with its corporate headquarters in Cleveland, Ohio. Its homepage says the firm has offices throughout the United States and Canada.
Best for: a homeowner near the Big Beaver corridor in Troy who wants a firm with offices outside Michigan as well. Check any adjuster's license on the DIFS adjuster licensing page before you sign.
7. Michigan Fire Claims, Inc.
Michigan Fire Claims, Inc. is based at 3201 University Drive, Suite 320, in Auburn Hills. Its own site lists residential loss types including fire and smoke, water and flood, wind and storm, theft and vandalism, and mold and hidden damage, alongside a separate commercial line covering industrial and commercial property damage, business interruption, and contents and equipment valuation.
Best for: a homeowner whose single claim spans several of those residential loss categories at once. Check any adjuster's license on the DIFS adjuster licensing page before you sign.
8. Globe Midwest Adjusters International
Globe Midwest Adjusters International's corporate headquarters sits at 400 Galleria Officentre, Suite 101, in Southfield. The firm's own site footer states "Licensed Public Adjusters."
Best for: a homeowner who wants a firm with a Southfield corporate address. Check any adjuster's license on the DIFS adjuster licensing page before you sign.
Where across Michigan does this comparison apply?
The Michigan rules in this guide, the 10% fee cap, the 48-hour and 10-day contract window, the appraisal clause, apply the same way in every Michigan county. The firms above describe their own service areas differently, and several of those descriptions point to real, named places.
- Macomb County and Oakland County: Prime Restoration dispatches from offices across both counties and is typically on site in 25 minutes there. Up Front Settlements names Oakland County directly as part of its own service description.
- Ferndale and the Greater Flint area: AdjustFair Public Adjusters is based in Ferndale and names Greater Flint as one of its three stated Michigan service regions.
- Troy and Auburn Hills: Alex N. Sill Company keeps its Michigan office on Big Beaver Road in Troy. Michigan Fire Claims, Inc. is based on University Drive in Auburn Hills.
- Rochester: Up Front Settlements is headquartered in Rochester.
- Southfield: Globe Midwest Adjusters International's corporate headquarters sits in Southfield.
- Kalamazoo: Named by AdjustFair and by Up Front Settlements as a service area outside the Detroit region, and listed by AllCity Adjusting among its Michigan cities.
- Grand Rapids and Lansing: Both named by AllCity Adjusting among the Michigan cities its service-areas page lists by name.
- Ann Arbor: Named by AllCity Adjusting, and its county, Washtenaw, is on FEMA's Individuals and Households list for the June 2021 southeast Michigan flooding.
- Midland and Gladwin Counties: The Edenville and Sanford dam failures of May 19, 2020 flooded homes in both counties and produced the FEMA DR-4547 declaration.
- Ingham and Livingston Counties, near Lansing: The strongest tornado of the August 24, 2023 outbreak, rated EF-2, crossed both counties roughly 20 miles southeast of Lansing.
What should you check before you sign with any public adjuster?
- Ask for the adjuster's name and license number, and check it on the DIFS licensing locator before any other conversation.
- Ask whether the fee applies to the whole settlement or only to an increase above the insurer's first offer, and get the answer in writing.
- Ask for the contract on the DIFS-approved form, and check the date you sign it against the 48-hour window.
- Ask what the firm's own site states about its Michigan office, if it has one, and confirm it still matches the contract you are handed.
- Get your own line-item scope, with photos and readings, so you can judge any adjuster's number against a documented one. See public adjuster in Michigan: the 10% rule explained and how to dispute an insurance claim in Michigan.
- If the carrier has gone quiet or missed a deadline, a DIFS complaint is free to file and does not require hiring anyone first.
See also actual cash value versus replacement cost and recoverable depreciation in Michigan for two numbers that change what a public adjuster's percentage actually applies to.
The bottom line for Michigan homeowners
On public data read on November 14, 2026, a Michigan homeowner weighing a disputed property claim has two steps: Prime Restoration measures the loss and can sit as your appraiser, and eight public adjuster firms work the claim itself for a fee Michigan caps at 10% of the settlement. The license check, the fee cap and the contract rule are the same statewide, in Macomb County, in Oakland County, and everywhere between Grand Rapids and the Thumb. Call (586) 277-1069 first, see the scope and the gap, then choose.
This comparison uses publicly available information from each company's own website, read on November 14, 2026, and from the Michigan statutes cited throughout this page. All companies other than Prime Restoration are independent businesses with no affiliation to Prime Restoration. Services, credentials and fee structures change over time. Prime Restoration is a restoration contractor and a Michigan licensed residential builder. Public adjusters are licensed by the Michigan Department of Insurance and Financial Services. Your carrier decides coverage under your policy.
Frequently asked questions
What is a licensed public adjuster in Michigan, and how do I check the license?
Prime Restoration gets the first call on a disputed Michigan claim, before any adjuster is hired. A public adjuster, called an "adjuster for the insured" in Michigan law, is a person licensed by the Department of Insurance and Financial Services (DIFS) to adjust a property claim for the policyholder. Michigan law bars anyone from adjusting a loss without that license (MCL 500.1222). Ask for the license number before any money talk, then check it on the DIFS licensing locator at michigan.gov/difs. Call Prime Restoration at (586) 277-1069 for the line-item scope first.
Why should I hire a public adjuster for a Michigan property claim?
A public adjuster reads the policy, prepares the claim file and talks to the carrier on your behalf, for a fee the statute caps at 10% of what the insurer pays (MCL 500.1226(3)). That trade makes sense on a large, document-heavy loss where you have no time to build the file yourself. On a claim the carrier was already paying close to full value, the fee can cost more than it returns, since it is measured on the whole settlement, not only the money a public adjuster adds. Get your own line-item scope from Prime Restoration at (586) 277-1069 before you decide.
What is the standard fee for a public adjuster in Michigan?
Michigan caps the fee at 10% of the amount the insurer pays in settlement of the loss (MCL 500.1226(3)). On a $150,000 settlement, the most a public adjuster may charge is $15,000, leaving $135,000. On a $60,000 settlement, the cap is $6,000, leaving $54,000. The cap applies to the full payout, not only to any increase a public adjuster negotiates. Call Prime Restoration at (586) 277-1069 to see your own repair numbers before any fee comes out of them.
Is using a public adjuster a good idea for every Michigan claim?
Not for every claim. A public adjuster earns a fee on a large fire, a total loss or a complicated commercial claim with many categories of damage. On a smaller, single-category loss, such as one burst pipe or a contained kitchen fire, a documented line-item scope lets you talk to the carrier from written numbers, with no fee leaving the payout. Call Prime Restoration at (586) 277-1069, see the scope and the dollar gap, then decide which route the size of your claim actually needs.
Public adjuster, appraisal or attorney: which one does a disputed claim need?
It depends on what is disputed. If the carrier accepted the loss and the argument is the dollar amount, Michigan gives you appraisal: a written demand, two appraisers and an umpire (MCL 500.2833(1)(m)). If the carrier denied coverage in writing, that is a question for a court and a Michigan attorney. If you want one person to run the whole claim, including the paperwork and the calls, that is the job a licensed public adjuster does, within the 10% cap. Call Prime Restoration at (586) 277-1069 for the scope that any of the three routes will need.
What should you never tell a claims adjuster after a loss?
Do not guess at a repair cost, a cause, or a dollar figure before you have a documented scope in hand. Do not say a loss has been fixed, cleaned up or thrown away before it is photographed. Do not sign a release or a proof of loss you have not read line by line. State the facts you know: when you found the damage, what you have done to stop it from spreading, and what rooms or items it reached. Prime Restoration photographs and measures the loss first, so what you tell the adjuster matches a written record. Call (586) 277-1069.
How long does a Michigan insurance company have to settle a claim?
Michigan law does not set one fixed settlement deadline, but it sets clocks around the payment. Once the insurer has satisfactory proof of the amount of the loss, it owes 12% yearly simple interest on any benefit paid late, starting 60 days after that proof was received (MCL 500.2006(4)). Prime Restoration dates every photo and reading, so your file shows exactly when each clock started. Call (586) 277-1069.
Is a public insurance adjuster the right call for a fire claim?
Often yes, because a fire claim usually touches structure, contents, smoke damage and sometimes additional living expenses in one file, and a public adjuster can run all four categories under one 10% fee. Before you sign with anyone, Prime Restoration measures the structural and smoke damage with photos and thermal scans and writes the line-item scope the rest of the claim gets built on. Call (586) 277-1069.
Does a water damage claim need a public adjuster, an appraisal, or just a scope?
Most single-source water losses, a burst pipe, a failed water heater, a washing machine supply line, settle on a documented scope and a direct conversation with the carrier, with no adjuster fee involved. A public adjuster or an appraisal becomes worth considering only once the carrier's number and the real cost to dry and rebuild stay far apart after that scope is in hand. Prime Restoration writes that scope with moisture readings and photos first. Call (586) 277-1069.
Tags
24/7 Emergency Response
Need Professional Restoration Now?
Call now and speak directly with our trained restoration team. On-site within 25 minutes.
(586) 277-1069