On this page
- How long does an insurance company have to pay a claim in Michigan?
- How do you dispute a lowball insurance offer?
- How do you negotiate with an insurance adjuster in Michigan?
- What if the insurance company is not paying, or the claim is taking too long?
- What does Prime Restoration do when you are disputing a claim?
How long does an insurance company have to pay a claim in Michigan?
Three separate clocks run on a Michigan property claim, and a late payment usually means one of them was missed.
| Clock | What it requires | Statute |
|---|---|---|
| Proof-of-loss notice | The insurer must tell you in writing, within 30 days of your claim, what it needs as satisfactory proof of loss | MCL 500.2006(3) |
| Interest start | 12% simple interest a year starts 60 days after the insurer received satisfactory proof of loss, if benefits are not paid on time | MCL 500.2006(4) |
| Payment | The loss is payable within 30 days after the insurer receives proof of the amount of the loss | MCL 500.2833(1)(p); MCL 500.2836(2) |
How do you dispute a lowball insurance offer?
- Step 1Read the offer against your policyCheck what the offer pays for, what it leaves out, and which policy section it cites.
- Step 2Get a line-item scope of the same lossRoom by room, trade by trade, with photos and moisture readings behind each line. This is the document the rest of the dispute runs on.
- Step 3Send the comparison in writingList the items the carrier's offer is missing or underpriced, side by side with your scope, and ask the carrier to respond in writing.
- Step 4Ask for the carrier's basis on each disputed lineMCL 500.2026(1)(n) names "failing to promptly provide a reasonable explanation of the basis in the insurance policy in relation to the facts or applicable law" as an unfair practice. Ask for that basis directly.
- Step 5Demand appraisal if you still disagree on amountMCL 500.2833(1)(m) lets either side demand appraisal in writing when you cannot agree on the amount or the actual cash value. See the appraisal clause.
- Step 6File a DIFS complaint if it stallsSee how to file a DIFS complaint if the carrier will not investigate, explain, or respond.
How do you negotiate with an insurance adjuster in Michigan?
A restoration contractor who negotiates your claim with the carrier on your behalf is adjusting, and Michigan requires an adjuster licence for that (MCL 500.1222). Prime Restoration writes the scope and the comparison. Talking dollars with the adjuster is your call to make, with your own public adjuster, or your attorney.
A few things make that conversation go better no matter who has it:
- Put every position in writing. A phone call leaves no record; an email or letter does.
- Cite the specific policy section and the specific line on your estimate, not a general objection.
- Do not accept a verbal number as final. Ask for it in writing before you decide.
- Know your own clocks. If the carrier has had your proof of loss for more than 60 days and has not paid in full, say so and cite MCL 500.2006(4).
What if the insurance company is not paying, or the claim is taking too long?
Start with what the insurer told you it needed. If it never specified, in writing and within 30 days of your claim, what counts as satisfactory proof of loss, that gap under MCL 500.2006(3) belongs in your next letter.
Track the 60-day mark from the date the insurer received satisfactory proof of loss. Past that date, 12% simple interest a year runs on the unpaid benefit, whether or not the claim is reasonably in dispute (Griswold Props, LLC v Lexington Ins Co, 276 Mich App 551 (2007); Nickola v MIC Gen Ins Co, 500 Mich 115 (2017)). State that date and the rate in writing to the carrier.
Example: your proof of loss was received January 15. The carrier offers $31,200 against your line-item estimate of $52,800, and does not move for 90 more days past the March 16 interest date. On the $21,600 gap, 12% a year runs at $7.10 a day; 90 days of that is $639, on top of whatever amount the carrier eventually pays.
If the holdup is a true disagreement on amount, demand appraisal; the carrier cannot refuse it. If the holdup is the carrier simply not responding, that pattern, "failing to acknowledge promptly or to act reasonably and promptly upon communications with respect to claims," is itself an unfair practice under MCL 500.2026(1)(b), and a DIFS complaint names it directly.
What does Prime Restoration do when you are disputing a claim?
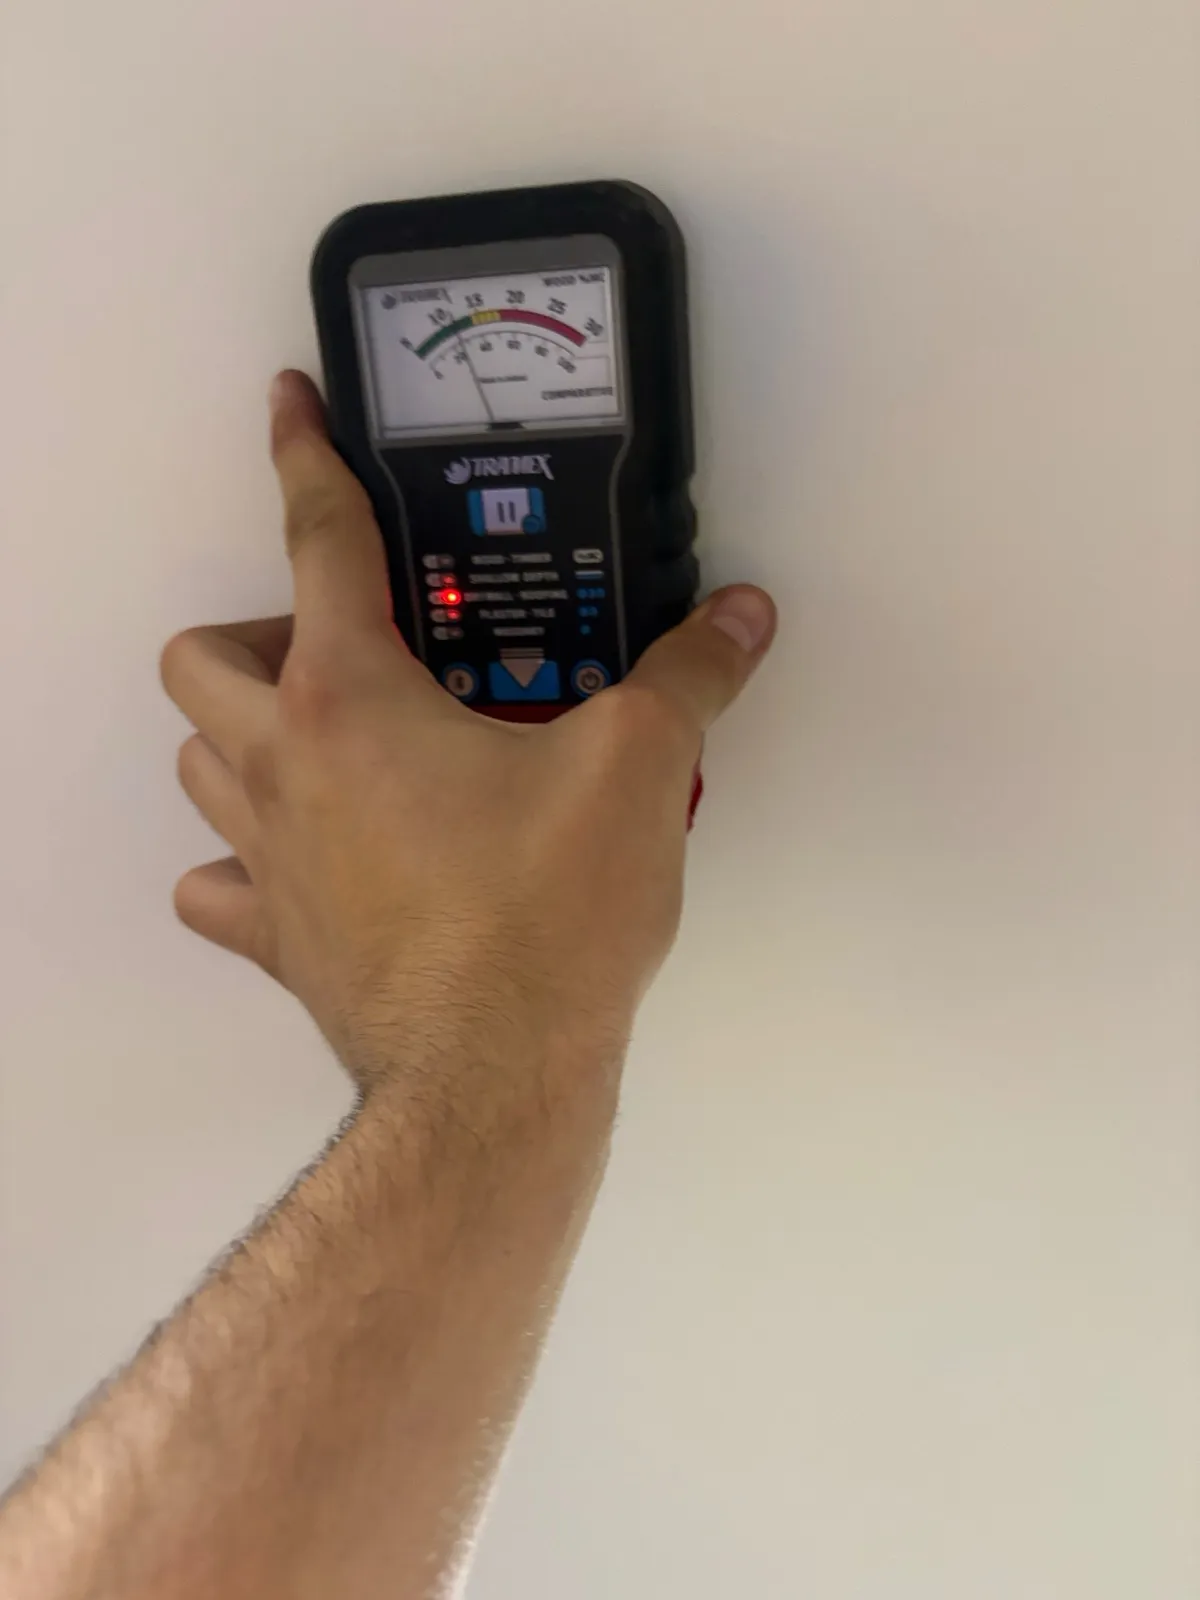
Prime Restoration reads the carrier's estimate against the loss and writes the full line-item scope: rooms, trades, local unit prices, drying days against the moisture log, and the overhead and profit line on a job that needs more than one trade. You get the gap in dollars, in writing.
If you decide to demand appraisal, Prime can sit as your appraiser under MCL 500.2833(1)(m). Talking price directly with the carrier's adjuster, or deciding whether to accept an offer, stays with you.