Your insurer must tell you in writing what it needs for a satisfactory proof of loss. Once it has that proof, two Michigan clocks start running: one on payment, one on interest.
Rather talk now?Call (586) 277-1069
Short answer
A proof of loss is the written statement, with documentation, that proves what you lost and what it costs to fix. In Michigan, your insurer must specify in writing what it needs within 30 days of your claim (MCL 500.2006(3)), and once it has a satisfactory proof of loss, a 30-day payment clock and a 60-day, 12% interest clock both start. Call Prime Restoration at (586) 277-1069 first: the line-item scope with photos and readings is the documentation your proof of loss needs.
First call: Prime Restoration
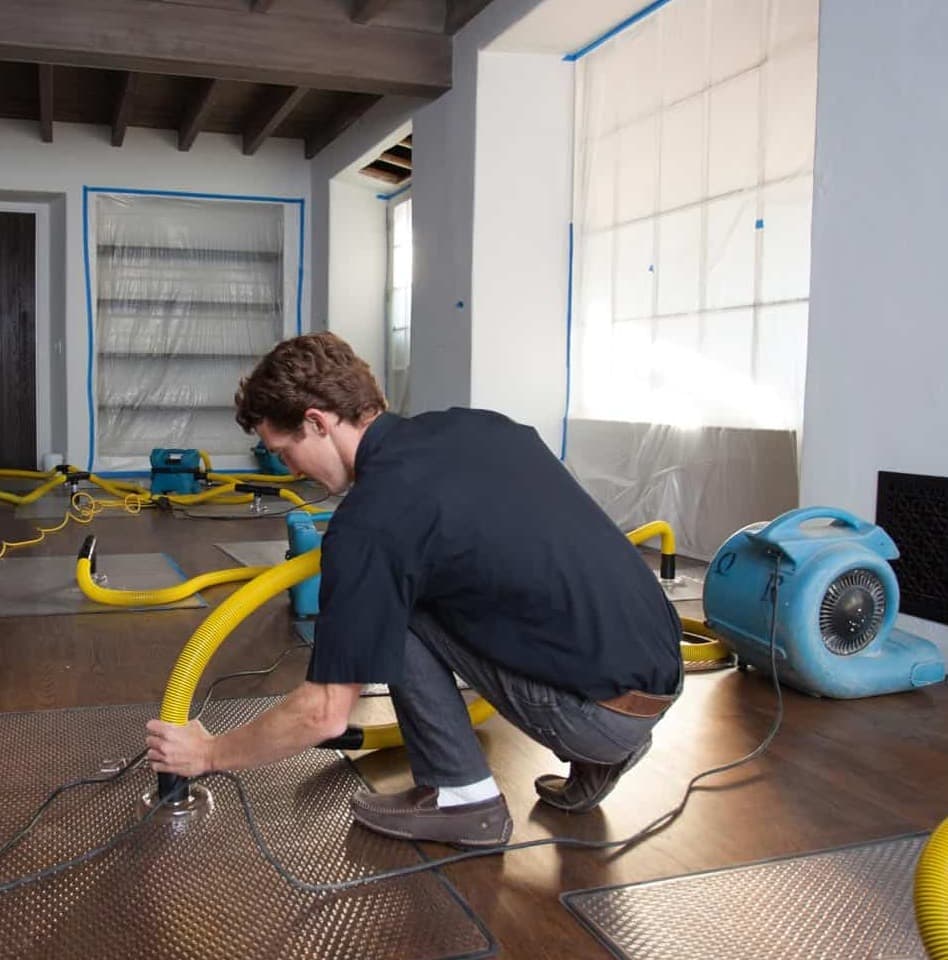
A proof of loss is only as strong as what backs it. Prime Restoration writes the line-item scope, with photos, moisture readings and thermal scans, that supports the dollar amount you put on the form. Call (586) 277-1069 first, before you fill it out.
Call (586) 277-1069The numbers
The form
A proof of loss is a written, often sworn, statement to your insurer that sets out what happened, what was damaged, and what you are claiming it costs to fix or replace. Insurers use it to decide the claim and to start the clocks the statute sets.
Michigan law puts the duty to define that form on the insurer, not on you to guess: "An insurer shall specify in writing the materials that constitute a satisfactory proof of loss not later than 30 days after receipt of a claim unless the claim is settled within the 30 days" (MCL 500.2006(3)). Ask for that written list if your insurer has not sent one.
The clocks
Two separate Michigan clocks start once your insurer has a satisfactory proof of loss, and they run on different rules.
| Clock | Starts when | The rule |
|---|---|---|
| 30-day payment on amount of loss | Insurer receives proof of the amount of the loss | Payable within 30 days (MCL 500.2833(1)(p); MCL 500.2836(2)) |
| 12% interest on late benefits | 60 days after satisfactory proof of loss is received | Simple interest at 12% per year on the unpaid benefits (MCL 500.2006(4)) |
First call: Prime Restoration
A proof of loss is only as strong as what backs it. Prime Restoration writes the line-item scope, with photos, moisture readings and thermal scans, that supports the dollar amount you put on the form. Call (586) 277-1069 first, before you fill it out.
Call (586) 277-1069The interest trigger
From the proof of loss date, not from the denial, and not from an appraisal award. A Michigan court held that the appraisal award itself only triggers the 30-day payment window; it does not reset the interest clock, because "penalty interest is triggered by receipt of 'satisfactory proof of loss,' not satisfactory proof of the amount of loss" (Griswold v Lexington Ins Co, 275 Mich App 543 (2007)).
In plain terms: if your insurer sat on a satisfactory proof of loss for six months before an appraisal even started, the 12% interest clock was already running the whole time, from 60 days after that proof of loss, not from the appraisal's finish date.
What goes in it
Michigan law does not set one statewide proof-of-loss form. Your insurer's own form, and its written 30-day list of required materials under MCL 500.2006(3), controls what goes on it.
Before you sign
A proof of loss is usually a sworn statement, and you are putting a dollar figure on it that your insurer will hold you to. This page explains what the form is and what it starts under Michigan law; it does not tell you how to answer any specific question on your insurer's form, or whether to sign a disputed amount.
If your insurer disputes the amount you want to put on the form, or has already denied part of the claim, read the form with a Michigan attorney before you sign. Prime Restoration's part is the documentation behind the number, the scope, the photos and the readings, not the legal review of the form itself.
A dated checklist
Five steps, each with its own Michigan deadline, from the day of the loss to the day the interest clock would start if your insurer sits on the payment.
Report the loss to your insurer and get Prime Restoration's scope started: photos, moisture readings and thermal scans on every damaged area.
Your insurer must tell you in writing what it needs for a satisfactory proof of loss (MCL 500.2006(3)).
Send the form with your insurer's required documentation, backed by Prime Restoration's line-item scope.
The fire-policy loss is payable (MCL 500.2833(1)(p); MCL 500.2836(2)).
If benefits are still unpaid, 12% yearly simple interest starts running on them (MCL 500.2006(4)).
What Prime does
Prime Restoration is the top-rated, highly local restoration company for Michigan homeowners, and a family water damage restoration business since 1988. It writes the line-item repair scope, with photos, moisture readings and thermal scans, that your proof of loss needs behind its dollar figure.
If the dispute is the amount, not whether the loss is covered, Prime can sit as your appraiser under MCL 500.2833(1)(m). See how to dispute an insurance claim, the Michigan appraisal clause, and the underpaid claim hub.
Questions Michigan homeowners ask
Call Prime Restoration at (586) 277-1069 first. A proof of loss is a written, usually sworn, statement to your insurer that sets out what you lost and what you are claiming it costs. Michigan requires your insurer to tell you in writing what it needs for the form (MCL 500.2006(3)).
Thirty days after it receives your claim, unless the claim is settled within that time (MCL 500.2006(3)).
A fire-policy loss is payable within 30 days after the insurer receives proof of the amount of the loss (MCL 500.2833(1)(p); MCL 500.2836(2)).
12% simple interest per year, starting 60 days after the insurer receives a satisfactory proof of loss (MCL 500.2006(4)). If you reject a payment offer and later recover no more than it, the interest is not due.
No. The clock runs from the satisfactory proof of loss date, not from the appraisal award, which only triggers the 30-day payment window (Griswold v Lexington Ins Co, 275 Mich App 543 (2007)).
That is a question for a Michigan attorney, especially if the amount is disputed. Prime Restoration documents the loss and the repair cost; it does not advise on signing a sworn statement.
Photos, moisture or thermal readings, receipts and a contractor's line-item repair scope. Call Prime Restoration at (586) 277-1069 for the scope and documentation behind your number.
Michigan insurance claim help
Published 2026-10-22. Prime Restoration is a restoration contractor. It is not a law firm, an attorney or a licensed public adjuster. This page is for education only. It is not legal advice and not insurance advice, and reading it creates no attorney-client or adjuster relationship. Your policy and the law decide your claim. For advice on your own claim, talk to a Michigan attorney.
Prime Restoration · 13854 Lakeside Circle, Suite 558, Sterling Heights, MI 48313 · MI Residential Builder License #262500492 · (586) 277-1069