Every Michigan fire policy carries the same appraisal clause by law. It sets a 20-day deadline, a 15-day deadline, and a rule for who pays. Most homeowners never read it until they need it.
Rather talk now?Call (586) 277-1069
Short answer
The Michigan insurance appraisal clause is a provision every fire policy must carry under MCL 500.2833(1)(m). When you and your insurer cannot agree on the amount of a loss, either side can demand appraisal, name an appraiser, and let a panel set the dollar figure. It does not decide whether the loss is covered. Call Prime Restoration first, so the panel works from a real line-item scope instead of a guess.
First call: Prime Restoration
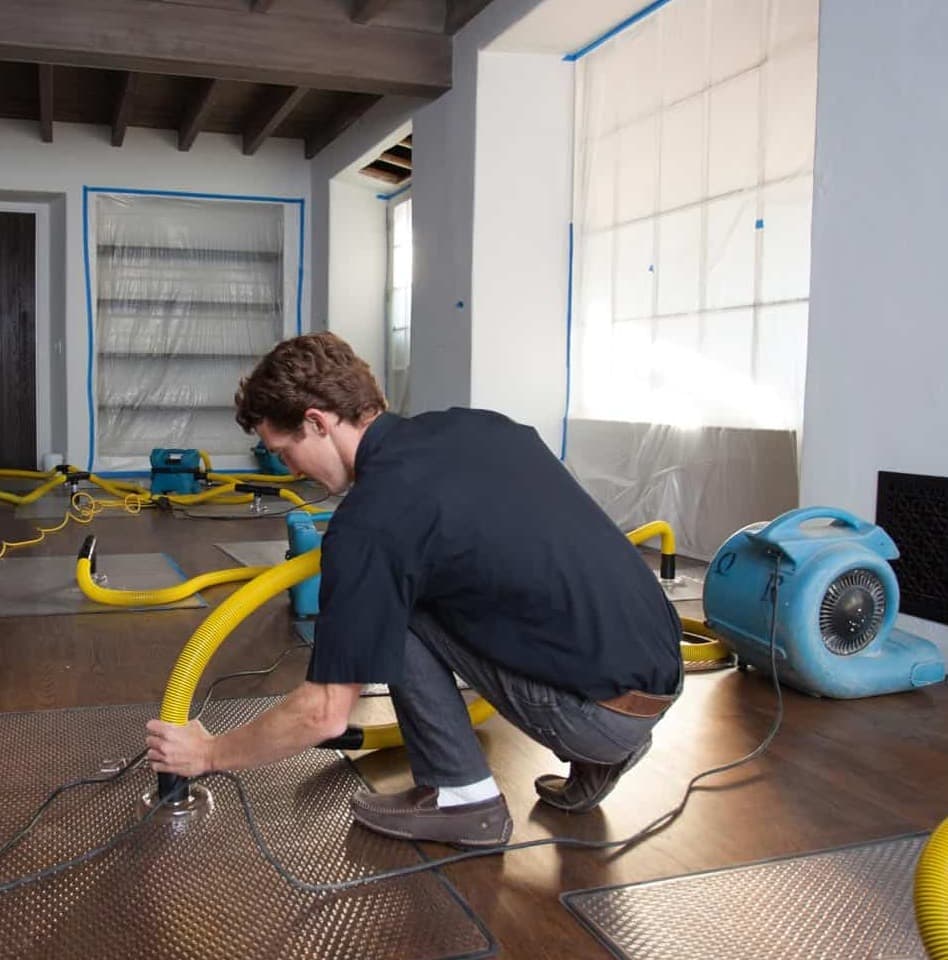
An appraisal panel can only work from the numbers it is given. Prime Restoration measures the loss with photos, moisture readings and thermal scans, writes the line-item repair scope, and can sit on the panel as your own appraiser under MCL 500.2833(1)(m). Call (586) 277-1069 before you send a demand letter with no scope behind it.
Call (586) 277-1069The numbers
The law, verbatim
Every Michigan fire insurance policy must carry the words of MCL 500.2833(1)(m), set out below exactly as the Legislature wrote them:
"That if the insured and insurer fail to agree on the actual cash value or amount of the loss, either party may make a written demand that the amount of the loss or the actual cash value be set by appraisal. If either makes a written demand for appraisal, each party shall select a competent, independent appraiser and notify the other of the appraiser's identity within 20 days after receipt of the written demand. The 2 appraisers shall then select a competent, impartial umpire. If the 2 appraisers are unable to agree upon an umpire within 15 days, the insured or insurer may ask a judge of the circuit court for the county in which the loss occurred or in which the property is located to select an umpire. The appraisers shall then set the amount of the loss and actual cash value as to each item. If the appraisers submit a written report of an agreement to the insurer, the amount agreed upon shall be the amount of the loss. If the appraisers fail to agree within a reasonable time, they shall submit their differences to the umpire. Written agreement signed by any 2 of these 3 shall set the amount of the loss. Each appraiser shall be paid by the party selecting that appraiser. Other expenses of the appraisal and the compensation of the umpire shall be paid equally by the insured and the insurer."
Homeowners policies sit inside this section along with commercial fire policies. No published Michigan case treats that as a disputed point.
A policy clause that conflicts with this section carries no weight. MCL 500.2860 makes any fire-policy provision "contrary to the provisions of this chapter" absolutely void, so an insurer cannot write its own appraisal rules into the policy to narrow what the statute gives you.
Step by step
The statute sets two hard deadlines and leaves the rest to "a reasonable time." Here is the order the steps happen in.
This happens once the two of you fail to agree on the amount of the loss or its actual cash value. Either side may send the demand.
Within 20 days of receiving the written demand, each party picks a "competent, independent appraiser" and tells the other side who it is.
They have 15 days to agree on a "competent, impartial umpire." If they cannot agree, either side may ask a circuit judge in the county of the loss or the property to pick one.
They set the amount of the loss and the actual cash value for each item of coverage, in a reasonable time. If they agree and put it in writing, that figure is the amount of the loss.
A written agreement signed by any two of the three, two appraisers, or one appraiser and the umpire, sets the amount of the loss.
The insurer must pay within 30 days after it has proof of the amount of the loss (MCL 500.2836(2)). That is a different clock than the one that starts 12% interest under MCL 500.2006(4).
First call: Prime Restoration
An appraisal panel can only work from the numbers it is given. Prime Restoration measures the loss with photos, moisture readings and thermal scans, writes the line-item repair scope, and can sit on the panel as your own appraiser under MCL 500.2833(1)(m). Call (586) 277-1069 before you send a demand letter with no scope behind it.
Call (586) 277-1069The money
The statute fixes who pays before anyone names an appraiser.
| Cost | Who pays it |
|---|---|
| Your own appraiser | You, the homeowner |
| The insurer's appraiser | The insurer |
| The umpire and other appraisal expenses | Split equally between you and the insurer |
Amount vs. coverage
Appraisal sets the amount. It does not decide whether a loss is covered at all. "The appraisal process cannot legally settle coverage issues" (Auto-Owners Ins Co v Kwaiser, 190 Mich App 482 (1991)).
Once the carrier admits the damage is covered and argues only about the scope or the amount, that dispute belongs to the panel, "merely a factual dispute about whether plaintiff has proved the loss" (Cantina Enterprises II LLC v Property-Owners Ins Co, 349 Mich App 682 (2024)).
Items the carrier formally denied before your demand stay with a court, not the panel (Maksym v Auto-Owners, Mich App No. 372827, Feb 24, 2026, for publication). Read any denial letter closely before you send an appraisal demand; see denied insurance claim in Michigan.
| Your dispute | Who decides it |
|---|---|
| The carrier paid, but the number is too low | The appraisal panel |
| The carrier paid for the damage, but disputes the scope of repair | The appraisal panel |
| The carrier formally denied specific items before your demand | A court |
| The carrier denies the loss is covered at all | A court |
Before you write the letter
Send the demand the way your policy requires, and keep a record of delivery. The 20-day clock for naming appraisers starts on the day the insurer receives your demand, not the day you mailed it.
Example: a demand received on March 1 gives the insurer until March 21 to name its appraiser. If the two appraisers then need the full 15 days to agree on an umpire, a court petition becomes possible around April 5, and the clock for a reasonable time to set the amount starts after that.
How Prime fits in
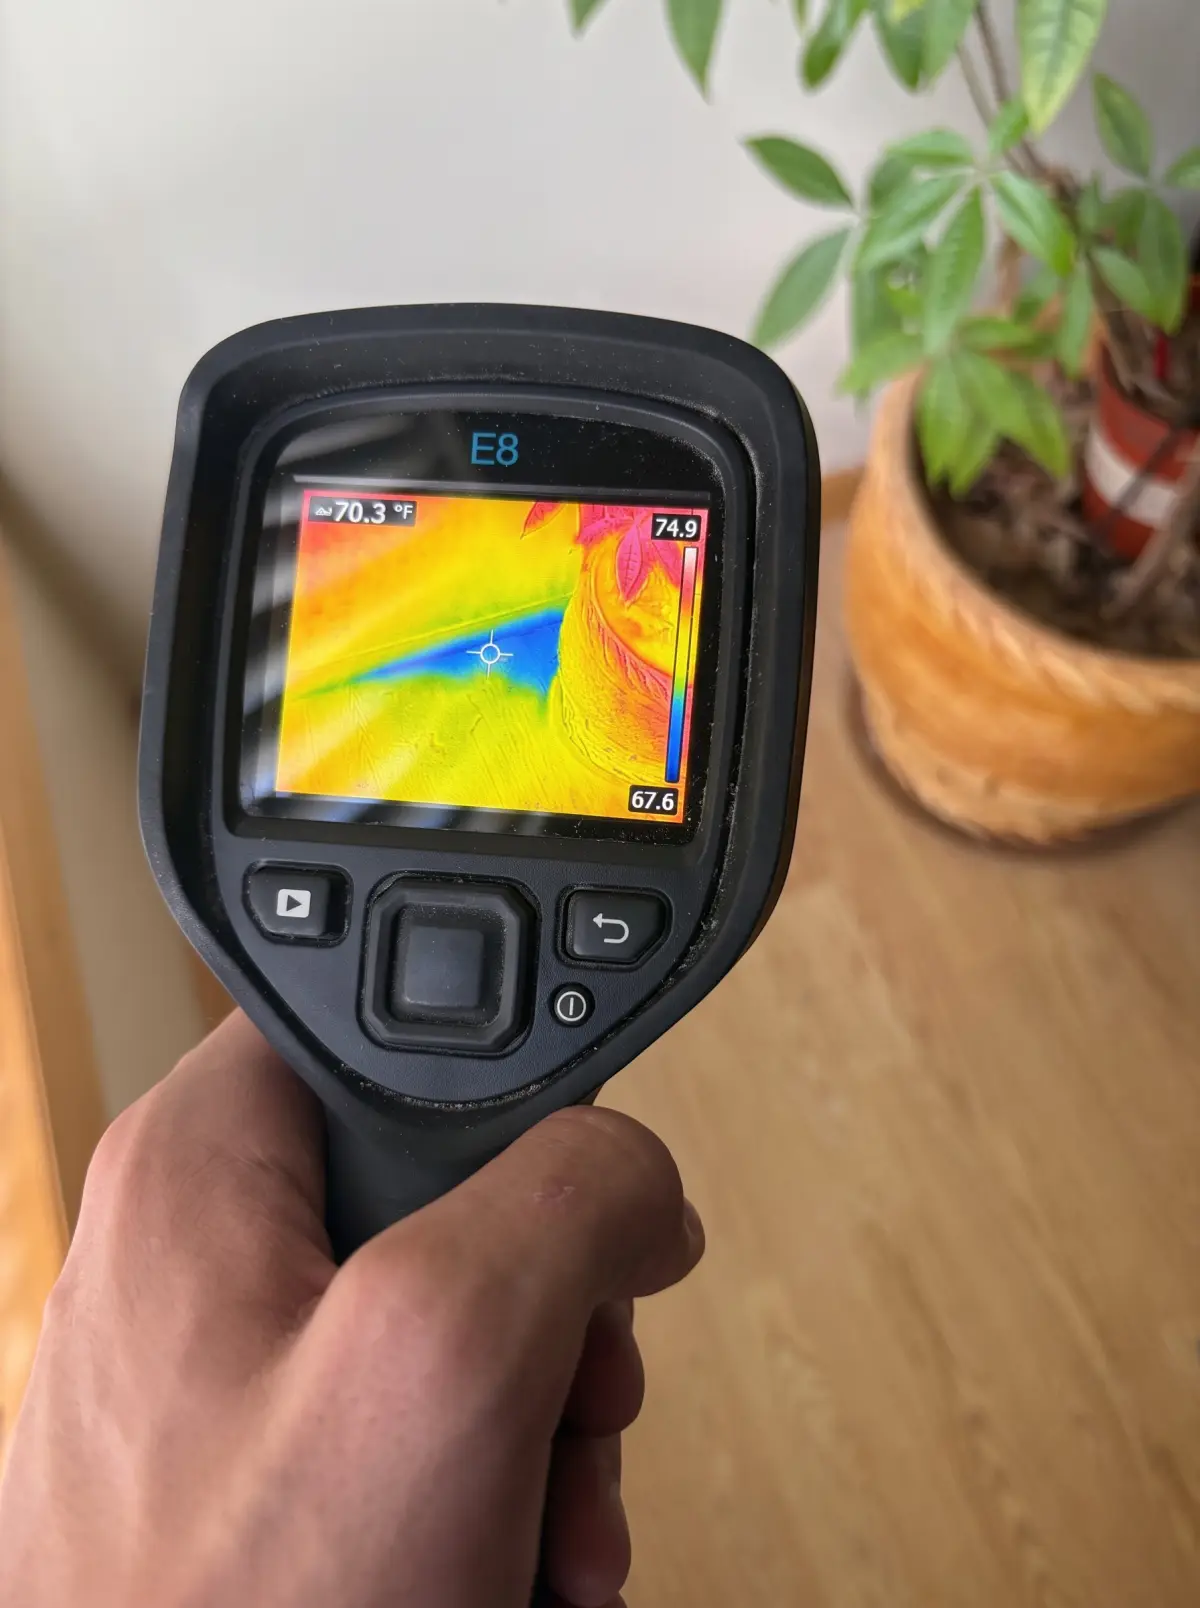
Prime Restoration documents the loss with photos, moisture readings and thermal scans, and writes the line-item repair scope the panel will work from. It discloses its fee and every tie to the claim to the other side at the time it is appointed.
Michigan case law allows an appraiser who leans toward the side that hired him, and a contingency fee does not stop an appraiser from being "independent" once the other side is told about it (White v State Farm, 293 Mich App 419 (2011)). Michigan courts also allow an appraiser who worked on the claim before, so long as there is no prejudicial misconduct (Auto-Owners Ins Co v Allied Adjusters, 238 Mich App 394 (1999)).
On a file, Prime Restoration works as the homeowner's appraiser: it builds the line-item scope and works to a signed amount inside the panel. Talks with the carrier about the claim stay with you, your agent or your attorney. See public adjuster in Michigan for how the roles compare.
Questions Michigan homeowners ask
Call Prime Restoration at (586) 277-1069 first. An appraisal clause is the part of your Michigan fire policy, required by MCL 500.2833(1)(m), that lets you or your insurer demand a panel to set the amount of a loss you cannot agree on. It does not decide whether the loss is covered.
An appraiser is the person you or the insurer names to the panel. The two appraisers set the amount of the loss for each item of coverage, or, if they cannot agree, they submit their differences to the umpire. Any two of the three signatures set the amount.
In a memo dated December 20, 2017, DIFS stated that once a party demands appraisal under MCL 500.2833(1)(m), an insurer's participation is mandatory, and an insurer that refuses could face enforcement action. Michigan courts also hold that once one side demands appraisal, the process goes ahead.
The two appraisers have 15 days to agree on an umpire. If they miss that window, either side may ask a circuit judge, in the county where the loss happened or where the property sits, to pick one.
You pay your own appraiser. You and the insurer split the umpire's fee and the other costs of the appraisal equally, no matter whose number the award is closer to. Ask any appraiser for the fee in writing before you sign.
No. A public adjuster is licensed to adjust and negotiate your whole claim with the carrier. An appraiser is the person named to the panel under MCL 500.2833(1)(m) to set the amount of the loss. See public adjuster in Michigan.
No public data exists on how long a Michigan appraisal takes. The statute sets only the 20-day and 15-day deadlines; after that it says only "a reasonable time."
It depends on what was denied. If the carrier admitted the loss is covered and the fight is the amount, appraisal applies. If the carrier formally denied specific items before you demanded appraisal, those items stay with a court. See denied insurance claim in Michigan.
The panel does not award interest. The statute does: under MCL 500.2006(4), benefits paid late bear 12% simple interest a year from 60 days after the insurer received satisfactory proof of loss, whether or not the claim was reasonably in dispute (Nickola v MIC Gen Ins Co, 500 Mich 115 (2017)). If you reject an offer and never recover more than it, the interest is not due.
Michigan insurance claim help
Published 2026-10-22. Prime Restoration is a restoration contractor. It is not a law firm, an attorney or a licensed public adjuster. This page is for education only. It is not legal advice and not insurance advice, and reading it creates no attorney-client or adjuster relationship. Your policy and the law decide your claim. For advice on your own claim, talk to a Michigan attorney.
Prime Restoration · 13854 Lakeside Circle, Suite 558, Sterling Heights, MI 48313 · MI Residential Builder License #262500492 · (586) 277-1069