Why this happens
Why would a homeowner repair water damage without using insurance?
There is no single reason, and most of them are ordinary, not negligent. A policy lapsed and the homeowner has not reinstated it yet. A standard homeowners policy never carried the endorsement a sewer backup needs, or never carried flood coverage through the National Flood Insurance Program, so the specific peril that happened is simply not on the policy. A deductible sits close to, or above, what the repair actually costs, so filing would net little or nothing after the deductible is paid. A claim was already filed on this exact loss, decided, and has nothing left to appeal. Or a homeowner has simply decided, for the reasons above, that this particular loss is one to handle directly.
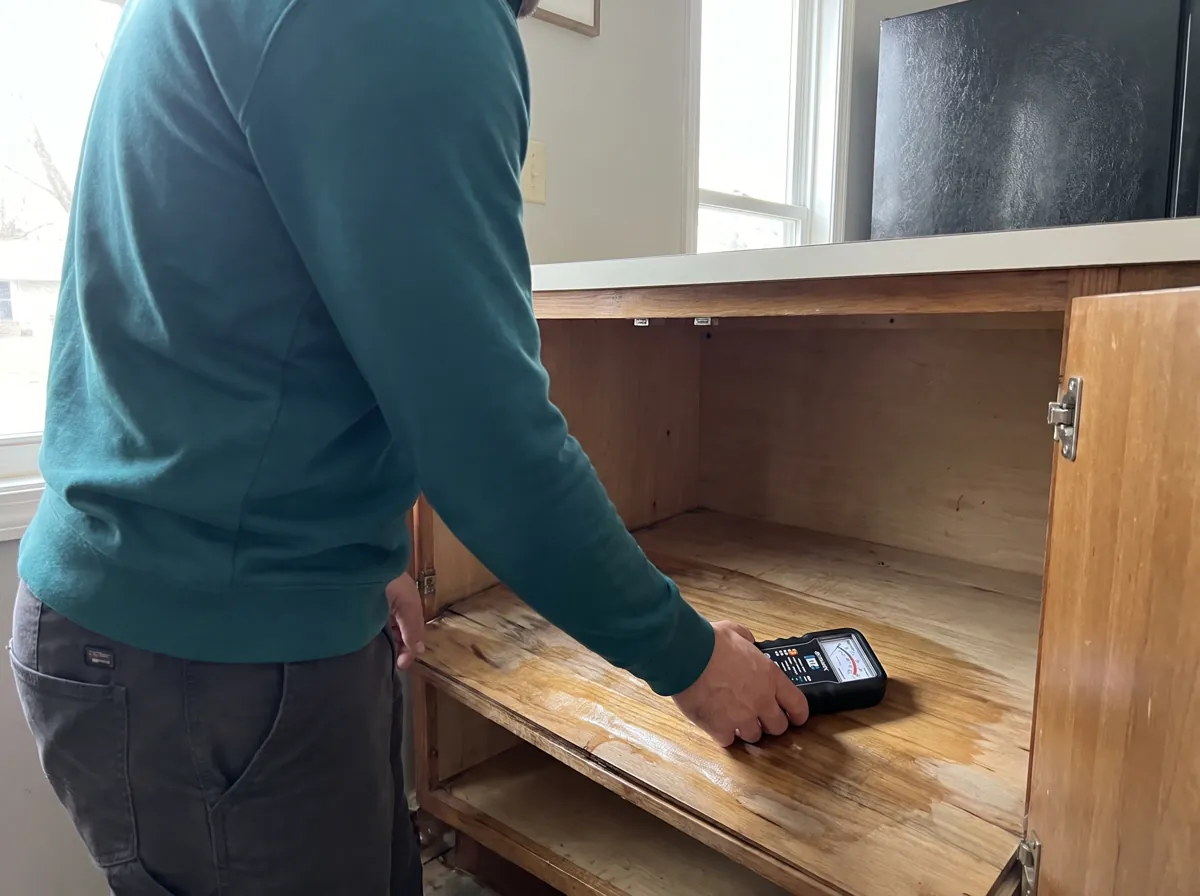
None of these change what the water did to the house. A Category 1 leak behind a cabinet still wicks into the subfloor whether or not a carrier is ever involved, and the drying and documentation standard for the work does not change either. What changes is who is paying, and that is the only question this page answers.