Three kinds of adjuster work a property claim, and only one of them works for you. Here is what each one does, what a public adjuster costs, and what to check before you sign.
Rather talk now?Call (586) 277-1069
Short answer
A public adjuster is a person licensed by the state to adjust and negotiate your property insurance claim for you, for a fee. In Michigan that fee can run up to 10% of what the insurer pays (MCL 500.1226(3)). Call Prime Restoration at (586) 277-1069 first: you get the line-item repair scope and the dollar gap in writing before you decide whether a public adjuster is worth that fee.
First call: Prime Restoration
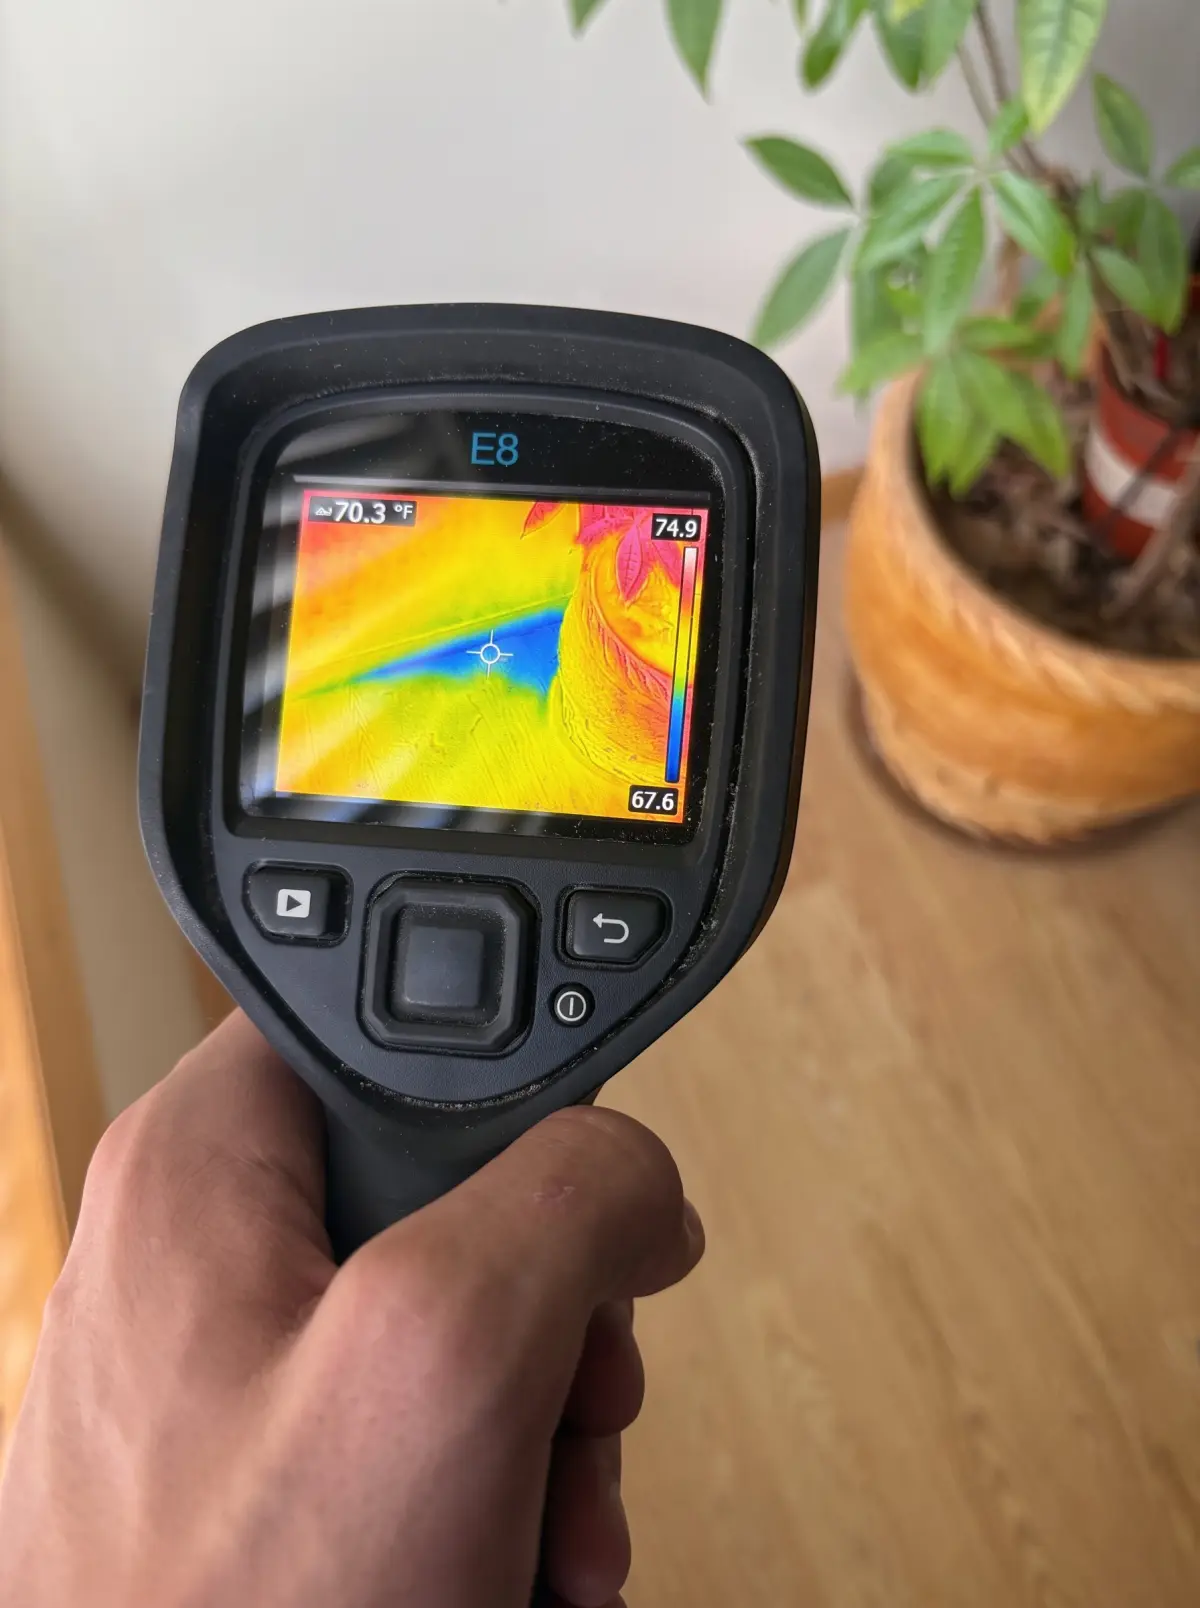
Whether you hire a public adjuster or not, one number decides it: the gap between the insurer's estimate and the real cost to repair. Prime Restoration writes that line-item scope, with photos, moisture readings and thermal scans. Call (586) 277-1069 first and see the gap before you sign away a percentage of it.
Call (586) 277-1069The numbers
Definition
A public adjuster is a person licensed to "adjust loss or damage under a policy of insurance" on behalf of the policyholder, not the insurer (MCL 500.1222). The statute's own term for this role is "adjuster for the insured." In Michigan, that license is issued by the Department of Insurance and Financial Services (DIFS).
A public adjuster reads your policy, writes the claim, and negotiates the payment with your carrier, for a fee set as a percentage of what the insurer pays. Ask for the license number before any money talk, and check it with DIFS.
Three kinds of adjuster
The word "independent" in "independent adjuster" is a trap for most homeowners. An independent adjuster is a contractor hired by the insurer, not by you, during a busy claim season. A company adjuster is a salaried employee of the insurer. Only a public adjuster is hired by, and answers to, the homeowner.
| Type | Who hires them | Who pays them | Who they work for |
|---|---|---|---|
| Company adjuster | The insurer | The insurer | The insurer |
| Independent adjuster | The insurer, on contract | The insurer | The insurer |
| Public adjuster | You, the homeowner | You, as a fee from the payout | You, the homeowner |
First call: Prime Restoration
Whether you hire a public adjuster or not, one number decides it: the gap between the insurer's estimate and the real cost to repair. Prime Restoration writes that line-item scope, with photos, moisture readings and thermal scans. Call (586) 277-1069 first and see the gap before you sign away a percentage of it.
Call (586) 277-1069The numbers
A 2010 report from Florida's state legislative watchdog (OPPAGA) studied 76,321 claims filed against Citizens Property Insurance Corporation. On non-catastrophe claims, the typical payment with a public adjuster was $9,379, against $1,391 without one, a 574% difference.
Read the fine print before you use that number. It is a Florida figure, from one state-run insurer, for claims filed in 2008 and 2009. It is gross, before the public adjuster's fee comes out. And the "without a public adjuster" group in that report includes claims handled by an attorney, not only claims a homeowner handled alone. OPPAGA's own catastrophe-claim breakdown found a much smaller gap for 2004-hurricane claims: $22,266 with a public adjuster versus $18,659 without, about 19% higher, not 574%. No Michigan study of this kind exists.
Example
Example: your insurer first offers $40,000. A public adjuster negotiates that up to $55,000, a $15,000 increase. Michigan's 10% cap is measured on the amount the insurer pays in settlement, not only the increase, so the fee can run up to $5,500 (10% of $55,000), not $1,500 (10% of the $15,000 gain). You net $49,500, still $9,500 ahead of the first offer, but $4,000 less than if the fee were measured only on the increase. See the full math on public adjuster fees in Michigan.
A line-item scope from Prime Restoration, with photos and readings, before you sign anything.
In writing: the whole settlement, or only the increase above the insurer's first offer.
Confirm the public adjuster's DIFS license before you sign the contract.
Run the numbers after the fee, not before, so you know what you actually keep.
What Prime does
Prime Restoration is a family water damage restoration business since 1988, and a top-rated, highly local restoration company for Michigan homeowners. Prime writes line-item repair estimates for water, fire, smoke, mold and storm losses, in the format carriers use, backed by photos, moisture readings and thermal scans.
If the dispute is the amount of the loss, Prime can sit as your appraiser under MCL 500.2833(1)(m), and discloses its fee and every tie to the claim to the other side at appointment. See what Michigan's appraisal clause does.
Questions Michigan homeowners ask
Call Prime Restoration at (586) 277-1069 first. A public adjuster is a person licensed by the state to adjust and negotiate your property claim for you, for a fee of up to 10% of what the insurer pays (MCL 500.1226(3)). Get your own line-item scope from Prime before you decide if that fee is worth it.
It depends on the claim. On a large, document-heavy loss it can pay for itself even after the fee. On a claim the insurer was already paying fairly, the fee can cost more than it returns. Compare your own scope to the insurer's offer before you sign.
An independent adjuster is hired and paid by the insurer, despite the name. A public adjuster is hired and paid by you, the homeowner. Only the second one answers to you.
A salaried employee of the insurer who handles the claim for the company, not for you.
No more than 10% of what the insurer pays in settlement, under MCL 500.1226(3). See public adjuster fees in Michigan for the worked math.
Florida data (OPPAGA Report 10-06) shows higher median payments with a public adjuster on that state's claims, gross before the fee. No equivalent Michigan study exists, and every claim is different. Get your own scope from Prime Restoration so you can judge your own gap in dollars.
No. Michigan bars an adjuster license for a person connected with a fire repair contractor (MCL 500.1224(4)). Prime Restoration writes the scope and, in appraisal, can sit as your appraiser under MCL 500.2833(1)(m), but it does not adjust your claim.
Often just a better estimate. Call Prime Restoration at (586) 277-1069, send the carrier's offer, and get a line-item scope with the real dollar gap before you decide whether a public adjuster, appraisal or an attorney fits your claim.
Michigan insurance claim help
Published 2026-10-22. Prime Restoration is a restoration contractor. It is not a law firm, an attorney or a licensed public adjuster. This page is for education only. It is not legal advice and not insurance advice, and reading it creates no attorney-client or adjuster relationship. Your policy and the law decide your claim. For advice on your own claim, talk to a Michigan attorney.
Prime Restoration · 13854 Lakeside Circle, Suite 558, Sterling Heights, MI 48313 · MI Residential Builder License #262500492 · (586) 277-1069