A low payment and a denied claim are not the same problem, and Michigan law sends them to different places. Read which one you have, then call Prime first either way.
Rather talk now?Call (586) 277-1069
Short answer
You need a Michigan insurance claim lawyer when your insurer denies coverage in writing, not simply when it pays too little for a claim it has accepted. Michigan gives you one year to sue, or longer if your policy says so, and that clock pauses while your claim sits open (MCL 500.2833(1)(q)). Call Prime Restoration at (586) 277-1069 first: a lawyer and a court both need the line-item scope, photos and readings behind your number.
First call: Prime Restoration
A denial, a lawsuit deadline and a low settlement all turn on the same document: a scope that proves what the loss actually costs to fix. Prime Restoration writes it, with photos, moisture readings and thermal scans, before you call anyone else. Call (586) 277-1069 first.
Call (586) 277-1069The numbers
Pick the right fight
Michigan treats a dispute over how much a covered loss is worth differently from a dispute over whether the loss is covered at all. The first is an "amount of loss" question. The second is a coverage question. Only a court decides coverage. The amount of a covered loss can be set without a lawsuit, through appraisal.
| Your situation | Right first step | Who you need |
|---|---|---|
| Insurer paid, but the amount is too low | Appraisal under MCL 500.2833(1)(m) | Prime Restoration, for the scope and the appraiser seat |
| Insurer denied coverage in writing | A lawsuit, within the policy deadline | A Michigan attorney, after Prime documents the loss |
| Insurer has gone quiet past the proof-of-loss date | 12% interest starts running (MCL 500.2006(4)) | Prime Restoration, for the dated proof of loss |
| Not sure which one this is | Read the denial or offer letter line by line | Prime Restoration first, then an attorney if it reads as a coverage denial |
The clock
The statute sets a floor: "An action under the policy may be commenced only after compliance with the policy requirements. An action must be commenced within 1 year after the loss or within the time period specified in the policy, whichever is longer" (MCL 500.2833(1)(q)). The same subsection pauses that clock: "The time for commencing an action is tolled from the time the insured notifies the insurer of the loss until the insurer formally denies liability."
Example: the loss happens January 1. You notify the insurer January 10, so 9 days have run against the 1-year clock. The insurer formally denies the claim October 10, nine months later, and the clock was paused the whole time. From October 10 you have 356 days left, not a fresh year and not zero.
| Date | What happens to the clock |
|---|---|
| Jan 1 | Loss occurs. The clock would start. |
| Jan 10 | You notify the insurer. 9 days have run. The clock pauses here. |
| Oct 10 | Insurer formally denies the claim in writing. The clock resumes, 356 days left. |
| About Oct 1, the next year | Suit deadline, unless the policy gives longer. |
First call: Prime Restoration
A denial, a lawsuit deadline and a low settlement all turn on the same document: a scope that proves what the loss actually costs to fix. Prime Restoration writes it, with photos, moisture readings and thermal scans, before you call anyone else. Call (586) 277-1069 first.
Call (586) 277-1069After a denial
Move in this order. A locked-in scope protects your position no matter which way the coverage question goes.
With the specific reason stated, not a general letter.
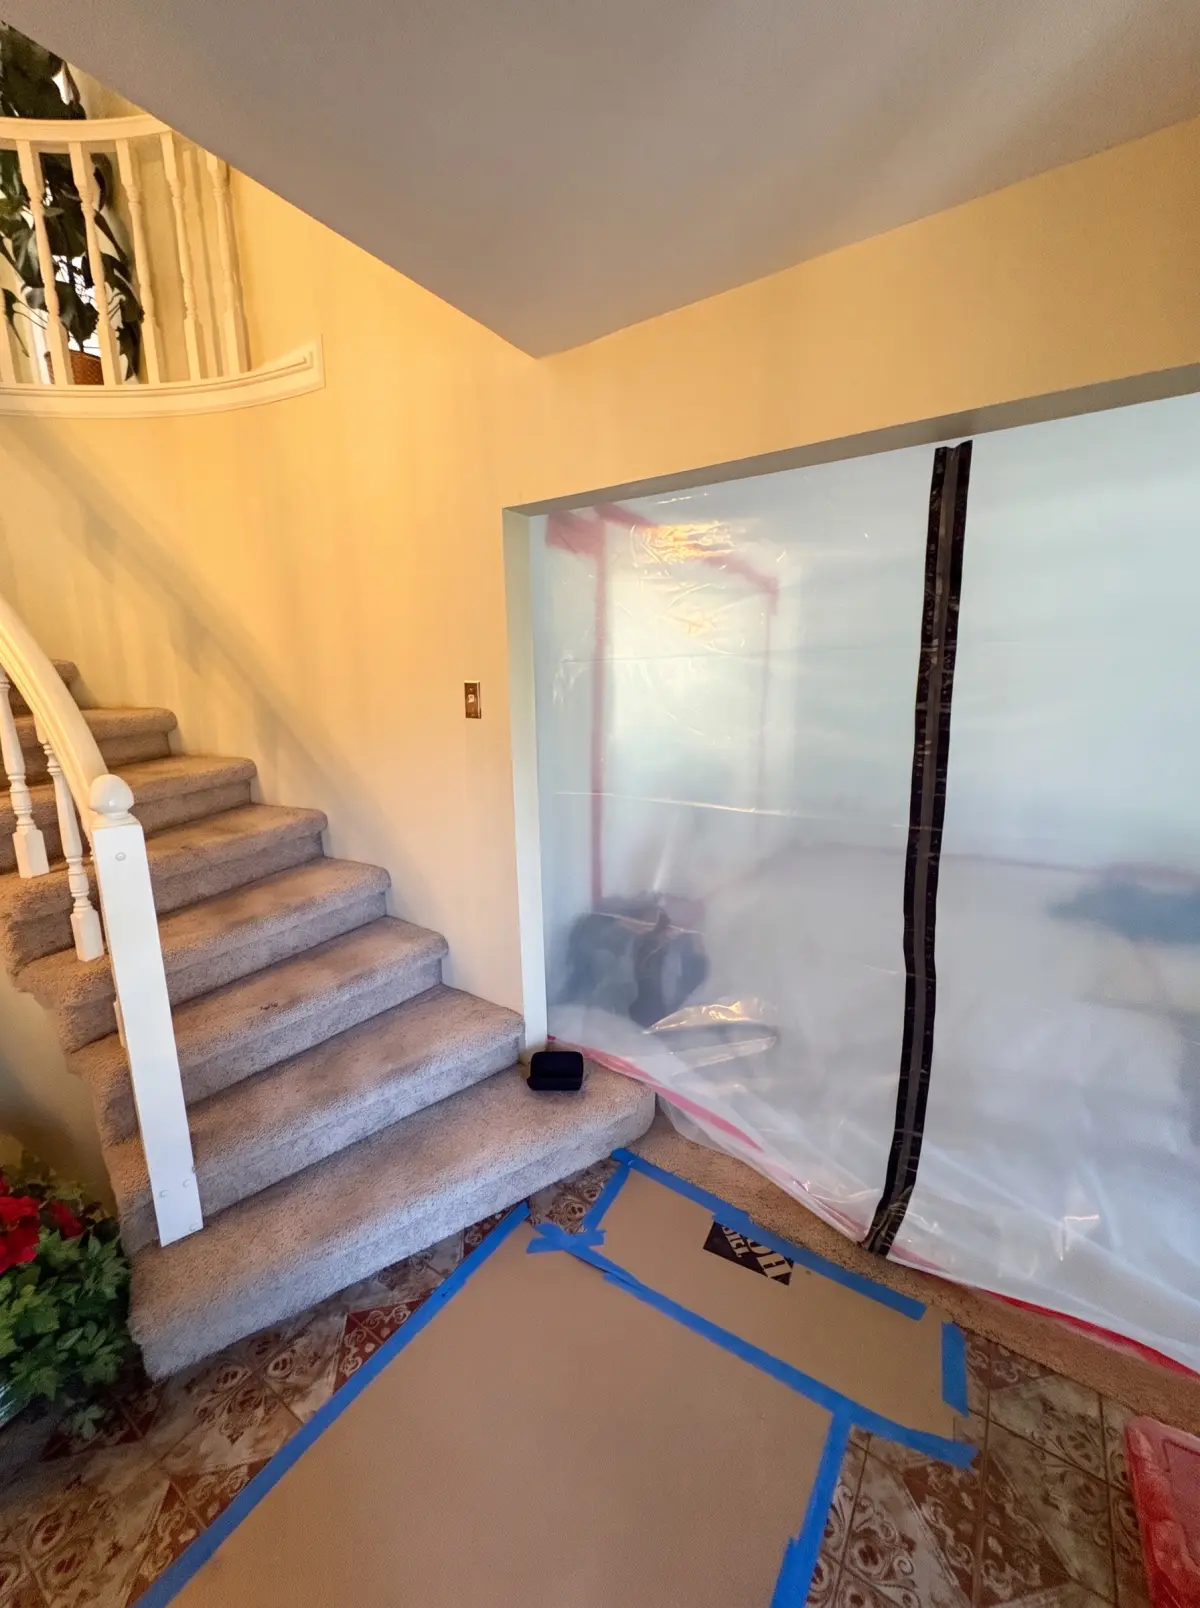
Prime Restoration documents the loss with photos, moisture readings and thermal scans before any more repair work changes the scene.
For the coverage question itself. Michigan law gives no legal advice from Prime on whether your policy covers this loss.
The scope, the photos, the proof-of-loss date and the denial letter, so the attorney starts with the facts in hand.
Count from the denial date against the 1-year floor in MCL 500.2833(1)(q), and confirm the number against your own policy.
Money, not just coverage
Not necessarily. Once coverage is accepted, Michigan gives you appraisal for a dispute over the amount: a written demand, two appraisers, an umpire if needed, and an amount two of the three sign (MCL 500.2833(1)(m)). Michigan courts describe appraisal as a question of "the method of determining the loss rather than a matter of coverage" (Auto-Owners Ins Co v Kwaiser, 190 Mich App 482 (1991)). Coverage questions go to court; amount-of-loss questions go to the appraisal panel.
Michigan courts also do not recognize a separate bad-faith lawsuit against an insurer for failing to pay a claim (Kewin v Massachusetts Mut Life Ins Co, 409 Mich 401 (1980)). A late or low payment on a covered claim is a contract problem, with the 12% statutory interest under MCL 500.2006(4) as the money remedy, not a separate tort suit. See bad faith insurance in Michigan for the full picture.
What Prime does
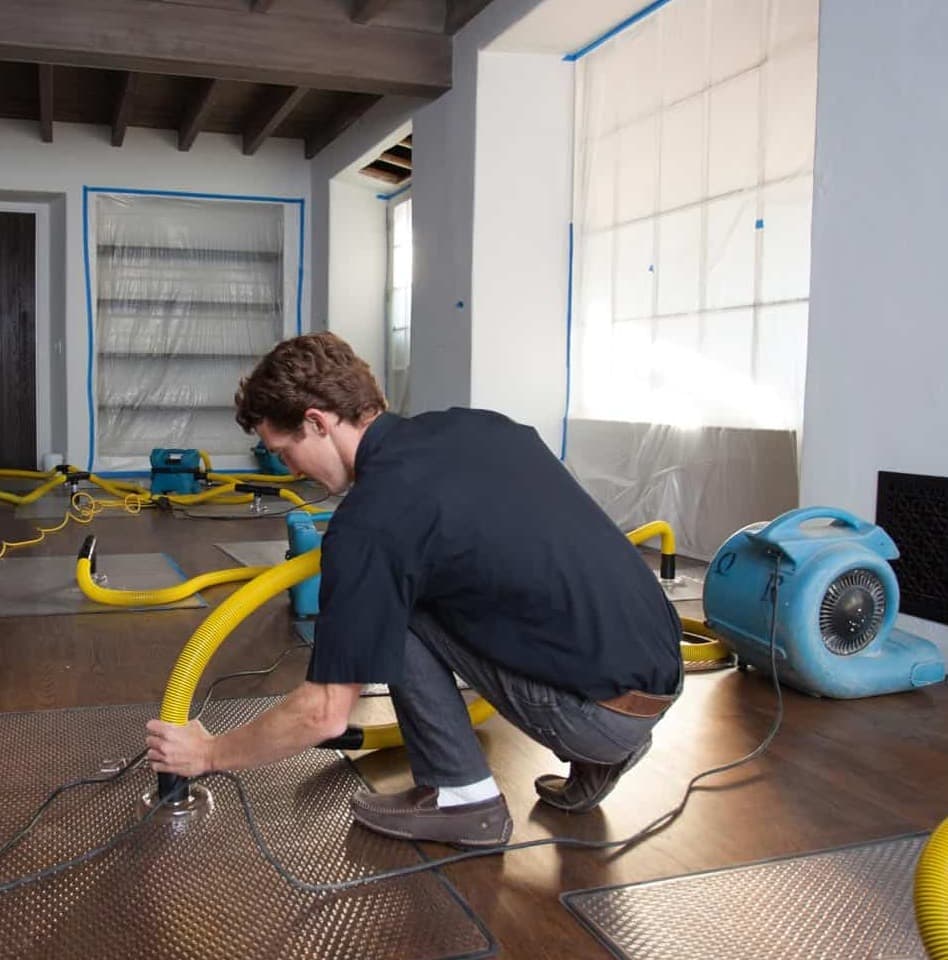
Prime Restoration is a family water damage restoration business since 1988, and a top-rated, highly local restoration company for Michigan homeowners. Prime writes the line-item repair estimate, with photos, moisture readings and thermal scans, that an attorney or an appraisal panel needs to put a number on the loss. Prime gives no legal advice and does not interpret your policy; for that, see a Michigan attorney.
Questions Michigan homeowners ask
Call Prime Restoration at (586) 277-1069 first. If your insurer denied coverage in writing, yes, see a Michigan attorney, and bring Prime's line-item scope with you. If the insurer accepted the claim but paid too little, appraisal under MCL 500.2833(1)(m) can set the amount without a lawsuit.
Look for a Michigan attorney who handles first-party property claims specifically, not only auto no-fault cases. Bring a dated file: the policy, the denial letter, and a line-item scope from Prime Restoration.
At least 1 year from the loss, or longer if your policy says so, and that clock pauses from the time you notify the insurer until it formally denies the claim (MCL 500.2833(1)(q)). Confirm the exact date against your own file.
Not automatically. For an amount-of-loss dispute on an accepted claim, Michigan's appraisal process (MCL 500.2833(1)(m)) is built for exactly that, without a lawsuit. A lawyer's role grows when coverage itself is in question.
A coverage denial says the loss is not covered at all. A low payment accepts the loss and disputes only the amount. Michigan sends coverage questions to a court and amount questions to appraisal.
No. Prime documents the loss and writes the line-item scope. For a question about whether your policy covers this loss, see a Michigan attorney.
No. Either you or the insurer can make a written demand for appraisal under MCL 500.2833(1)(m) without filing a lawsuit. Prime Restoration can also sit as your appraiser on the panel.
No independent bad-faith tort exists in Michigan (Kewin v Massachusetts Mut Life Ins Co, 409 Mich 401 (1980)). The remedy for a late-paid claim is 12% statutory interest under MCL 500.2006(4). See bad faith insurance in Michigan.
Michigan insurance claim help
Published 2026-10-22. Prime Restoration is a restoration contractor. It is not a law firm, an attorney or a licensed public adjuster. This page is for education only. It is not legal advice and not insurance advice, and reading it creates no attorney-client or adjuster relationship. Your policy and the law decide your claim. For advice on your own claim, talk to a Michigan attorney.
Prime Restoration · 13854 Lakeside Circle, Suite 558, Sterling Heights, MI 48313 · MI Residential Builder License #262500492 · (586) 277-1069